India’s new maritime growth model
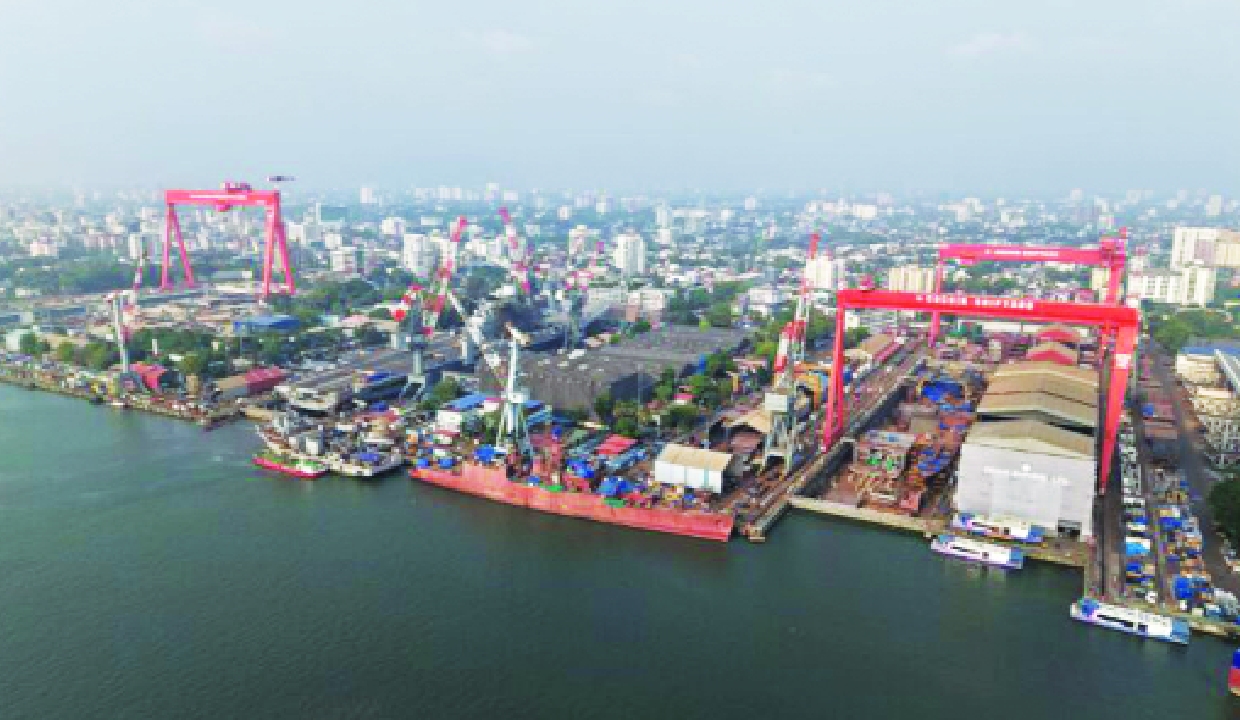
India, as the world leader in ship recycling, is simultaneously seeking to increase its shipbuilding capabilities manifold as an integral part of its maritime transformation, which is being shaped by two major long-term frameworks: the Maritime India Vision 2030 (MIV 2030) and the Maritime Amrit Kaal Vision 2047 (MAKV 2047). MIV 2030 and MAKV 2047 are not only about increasing the number of ships built in India; they represent a broader attempt to develop maritime capacities and capabilities across infrastructure, shipping, shipbuilding, repair, recycling, technology and human capital. The MIV 2030 seeks to position India among the world’s top 10 shipbuilding and repair nations, while the MAKV 2047 ambitiously aims to place India among the top five global shipbuilding nations while maintaining its numero uno position in ship recycling. The Union Budget 2025-26 has provided the much-needed fillip to the maritime sector, with substantial budgetary allocations for new shipbuilding clusters, modernisation of existing shipyards, the Maritime Development Fund and an enhanced Shipbuilding Financial Assistance Policy/Scheme (SBFAP/SBFAS) 2.0. The GoI has earmarked `18,090 crore for SBFAS 2.0, while the proposed shipbuilding clusters are envisaged at capacities of more than 1.0 million gross tonnage each. Within this larger transformation, the Ship Recycling Credit Note (SRCN) directly connects two important activities — ship recycling and shipbuilding – that have traditionally been treated separately.
Killing ‘more-than-two’ birds with one stone
The basic mechanism is simple and straightforward. A shipowner, on recycling an end-of-life (EOL) vessel at a Hong Kong Convention-compliant Indian recycling yard, would receive a credit note equivalent to 40 per cent of the vessel’s fair scrap value. The credit note is valid for three years from completion of recycling and can subsequently be used towards the construction of a new vessel in an Indian shipyard, with an offset of up to 5 per cent of the fair price of the new vessel. The credit note can also be stacked, partially utilised and transferred, with market-driven pricing. The credit note effectively creates a closed-loop economic pathway, with an additional economic incentive for the shipowner to recycle the EOL ship in India and potentially convert part of the vessel’s fair scrap value into a discount for the construction of the next vessel in an Indian shipyard, thus boosting the attractiveness of shipbuilding in India. Financial flexibility is also afforded to the shipowner to trade the SRCN within three years of issue, at a market-determined value.
The Ministry of Ports, Shipping and Waterways has championed this scheme as an instrument to incentivise both EOL ship recycling and new ship construction in India. There is also a broader industrial implication. Ship recycling is traditionally viewed as an end-of-life activity. The credit note reframes it as one component of a larger maritime manufacturing cycle. For India, this matters because strengthening shipbuilding requires not only new yards and financial assistance, among other influencing factors, but also a stable new-build demand. SBFAS 2.0 provides direct financial assistance to Indian shipyards to address cost disadvantages and bolster their ability to secure orders. The credit note complements this by creating an additional route through which shipowners can be encouraged to place new-build orders with Indian shipyards. Ship recycling activity supports material recovery and generates employment while directing end-of-life vessels towards compliant facilities. The credit note, therefore, has the potential to bring shipbuilding and ship recycling into a more interdependent relationship.
Why this matters for shipowners
For shipowners, the value proposition is not simply the additional monetary benefit. The more significant aspect is the possibility of integrating fleet renewal and end-of-life decisions. An owner planning to retire an older vessel can consider three linked elements: the residual scrap value, the credit generated through HKC-compliant Indian recycling, and the potential reduction in the cost of a subsequent Indian-built vessel. The transferability and stacking provisions also provide greater flexibility than a narrowly structured one-time subsidy. The mechanism could, therefore, become particularly relevant as fleet renewal accelerates and shipowners face increasing pressure to consider environmental performance, regulatory compliance and life-cycle costs alongside conventional commercial considerations.
The passage ahead
The real test will be implementation: ensuring transparent valuation of scrap, efficient issuance and redemption of credit notes, adequate awareness among domestic and international shipowners, and continued development of compliant recycling facilities and competitive shipyards. If these elements work together, the SRCN could become an important building block in India’s emerging circular maritime economy – where the end of one vessel’s life can help finance the beginning of another, within the country’s own maritime ecosystem. It augurs well that, as of September 21, 2026, four SRCNs have already been issued and more are being processed. In essence, the SRCN has the potential to boost both ship recycling and shipbuilding in India and catalyse India’s ongoing maritime transformation.
Cmdr Debesh Lahiri (Retd), Advisor, Resource Efficiency & Governance, TERI, and Ayushi Srivastava, Associate Fellow, Resource Efficiency & Governance, TERI; Views presented are personal.