Five-day staff, seven-day banking: Modernising India’s banks
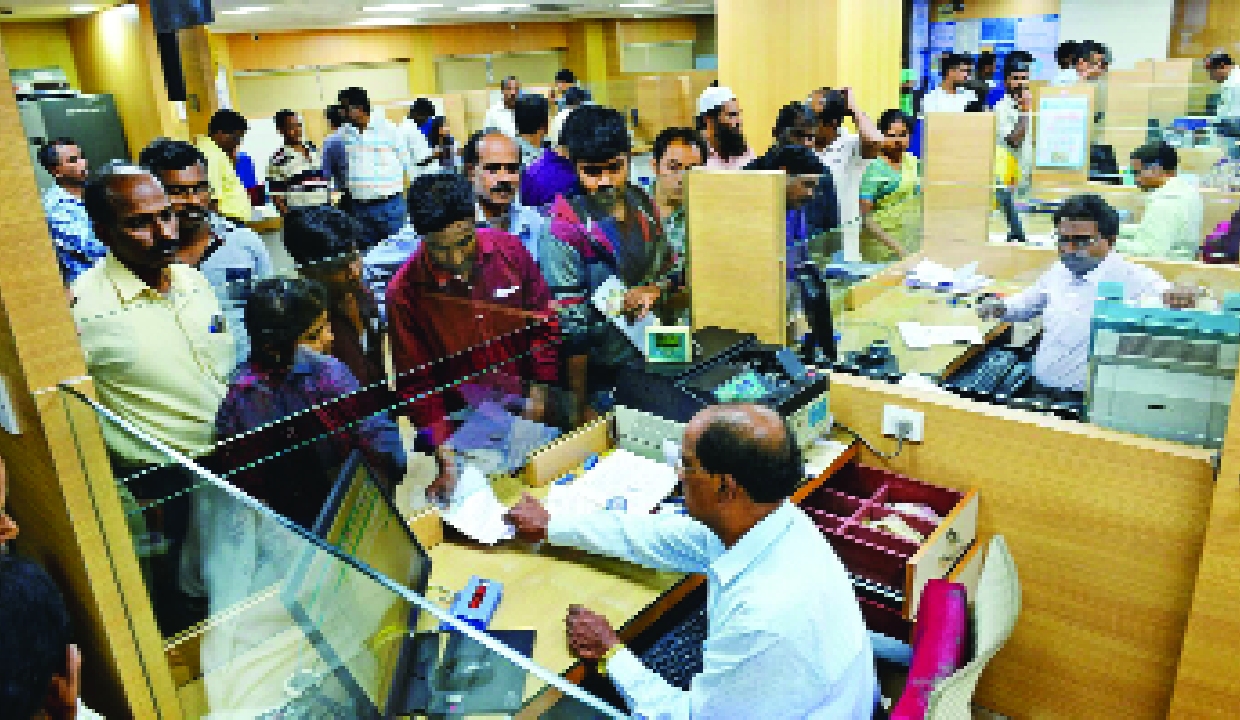
A bank employee should have a sustainable working life. A customer should be able to access banking services when needed. These two expectations should not be treated as competing interests.
India’s banking industry should now consider a five-day working week for its employees, alongside a clear commitment to keeping essential banking services available throughout the week. This is more than a question of an additional holiday. It is an opportunity to modernise the way banks organise their people, branches and technology around customer needs.
The banking customer has changed significantly. The traditional branch remains important, but it is no longer the only gateway to financial services. UPI, IMPS, NEFT, RTGS, mobile banking, internet banking and ATMs have expanded access to payments and routine transactions beyond conventional branch hours. Account opening, deposits, lending and investment-related services are also increasingly supported by digital channels.
Banking has consequently become an activity that customers expect to access beyond the traditional working calendar. The financial system must respond to that expectation while recognising that not every customer has the same level of digital access or comfort.
The experience of alternate Saturdays offers a useful starting point. Indian banks have operated with the second and fourth Saturdays as holidays while continuing to provide services through digital channels and other arrangements. This demonstrates the scope for separating branch working days from broader financial service availability. It does not, however, remove the need to protect customers who depend on physical branches, cash services or personal assistance.
The retail sector provides a practical operating example. Supermarkets, pharmacies and other businesses remain open across the week by using shifts, technology and workforce planning. Their customer-facing hours do not require every employee to work every day. Banking has greater regulatory and systemic responsibilities, so the comparison has limits. The underlying principle remains relevant: continuous service and individual employee schedules can be designed separately.
The objective should be to build a banking system that is available when customers need it, without making six-day working the default expectation for every employee.
Customer centricity must remain central to this redesign. A five-day working week should not mean that customers lose meaningful access to banking services on weekends. Banks could assess which activities require continuous availability, which can be delivered digitally and which need physical assistance. Weekend branch access, where necessary, could be organised through rotating arrangements or other locally appropriate models, taking account of customer profiles, cash dependence and financial inclusion requirements.
A rural customer, senior citizen, small trader or MSME may have different needs from a digitally confident urban customer. A modernisation programme should recognise these differences rather than assume that technology has removed the need for branches. The measure of success must be better customer service and access, not simply fewer branch working days.
The workforce dimension deserves equal attention. Banking employees increasingly handle responsibilities involving credit assessment, compliance, cybersecurity, fraud prevention, customer relationships and technology-led transformation. These are demanding functions requiring professional judgement and sustained attention.
Work-life balance is therefore relevant to the long-term effectiveness of banking institutions. A more predictable working pattern can support employee wellbeing, talent retention and the attractiveness of banking careers. Banks compete with technology companies, fintechs and other professional services organisations for skilled professionals, including younger employees who place value on career growth, workplace culture and sustainable working arrangements.
A five-day week must nevertheless be implemented responsibly. Compressing existing workloads into five days could undermine the intended benefit. Banks would need to examine staffing, process efficiency, workload distribution and performance expectations. The aim should be a genuinely sustainable working model, not longer working hours concealed within a shorter calendar.
Operational resilience is equally important. Payment processing, cybersecurity, fraud monitoring, treasury functions and technology support require appropriate coverage beyond regular branch hours. Banks should organise these responsibilities through suitable shifts, specialist teams, on-call arrangements and escalation protocols. Not every employee needs to work every day, but every critical function must have clear accountability and adequate protection.
India’s financial ecosystem already provides relevant precedents. Many other financial-sector institutions operate on a five-day working week, while the Reserve Bank of India follows a five-day working schedule. Commercial banks have distinct customer-facing and systemic responsibilities, so their transition would require appropriate arrangements. However, these institutional examples support the case for examining whether a five-day workforce model can be designed without compromising service continuity.
The issue also has a global dimension. India’s banking sector is increasingly integrated with international financial markets, cross-border payments, treasury operations and global talent networks. International banking practices offer useful reference points, although India must adapt any model to its own regulatory framework, customer requirements and financial inclusion priorities.
The transition should therefore be supported by a practical policy framework. Banks and relevant authorities could identify essential services requiring all-days availability, establish expectations for physical customer access and monitor service quality during implementation. Customer complaints, transaction failures, cash access and the experience of vulnerable customer groups should inform the evaluation.
India’s banking industry has repeatedly adapted to major changes, from core banking and ATMs to mobile banking, UPI, digital lending and account aggregators. The organisation of banking work should evolve alongside this transformation.
Five-day banking should not be viewed merely as an employee concession. It should be considered as part of a broader effort to improve workforce sustainability, operational efficiency and customer service. The success of the change should be judged by whether customers retain reliable access, banks maintain resilience and employees gain a working life that can be sustained. A successful transition can advance the government’s customer-centric vision by ensuring continued access to banking, through physical branches or digital channels. Coordination among stakeholders can enable phased reform, safeguard service continuity, strengthen productivity and support a sustainable workforce.
India can build a financial system that remains available throughout the week while enabling its banking workforce to work within a meaningful five-day framework.
The authors are corporate advisor & senior banking leader; Views presented are personal.