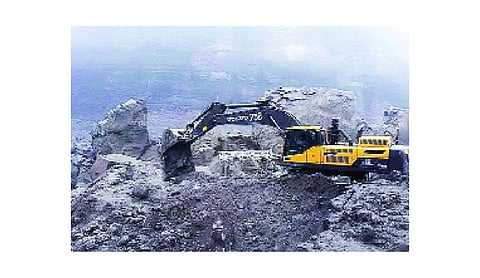
Refex Industries Ltd’s ash and coal handling business has reported an order book of Rs 1,721 crores at the end of quarter ending September 2026, up from about Rs 1,500 crores at the end of March 2026.
The company has a marquee clientele of NTPC and its joint ventures, Adani Power, Tata Power and several state power generation companies.
New orders have continued to flow in alongside robust execution.
The company’s ash & coal handling segment secured Rs 625 crores of fresh orders in the first six months of current financial year, a period in which the monsoon typically slows ash movement. The order inflow is showing up in the company’s results. Standalone revenue from continuing operations rose 54.7 percent to Rs 1,178.8 crores in the first half of current financial year, while EBITDA has grown 71.8 percent to Rs 195.9 crore.
"The Ash & Coal Handling business continues to see strong momentum, supported by robust orderbook and execution scale-up," said Anil Jain, Chairman and Managing Director of Refex Industries Ltd. The company has also moved further down the value chain. In September 2026, Refex launched its first ready-mix concrete plant in Pune on a capital-light model, which Jain described as a strategic forward integration. Cement and concrete are among the main uses for ash listed by the company.
Refex aims to operate 100+ plants by 2029. Refex Industries currently operates a fleet of over 2,000 owned and leased vehicles, serves more than 40 thermal power plants across 14 states and handles over 70,000 tonnes of ash a day.
The company has utilised more than 50 million tonnes of ash over the past eight years.
The company’s mobility business posted revenue of Rs 36 crores in the quarter and Rs 69 crores in the half-year. Jain said the mobility business is "progressing steadily towards profitability". Refex’s standalone debt-to-equity ratio stood at 0.10 as of March 2026.
In its August 2026 rating action, Acuité Ratings & Research said it expects the company’s operating performance to improve steadily, supported by its order book and ash handling execution.