Author: Aarushi Shanker
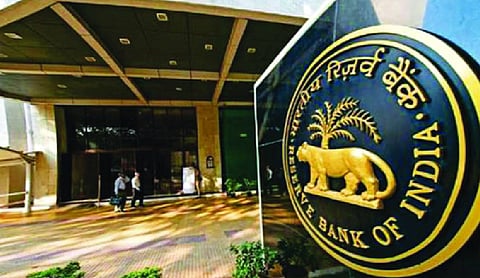
On October 7, 2026, the Reserve Bank of India’s (RBI) Monetary Policy Committee (MPC), chaired by Governor Sanjay Malhotra, unanimously decided to increase the repo rate by 25 basis points to 5.50 per cent, despite two members, Dr Nagesh Kumar and Prof. Ram Singh, preferring to keep the stance neutral. The central bank has hiked the rate for the first time since February 2023, signalling an end to the monetary easing cycle of 2025, which saw a total cut of 125 basis points.
In addition to hiking the policy rate, the RBI has also shifted its stance from neutral to calibrated tightening. This implies that the MPC has ruled out rate cuts in the near term, and any changes to the policy rate in the future would take the form of long-dated pauses or successive hikes as inflationary pressures start mounting. This decision would directly impact floating-rate home loan, auto loan and corporate lending interest rates for Indian households and businesses.
RBI’s inflation targeting: A precautionary measure
The reason for the October rate hike, rather than an earlier one in 2026, is reflected in the macroeconomic backdrop that preceded it. During the spring and summer months, domestic economic activity was picking up due to previous rate cuts. More importantly, inflation stayed within the RBI’s 2-6 per cent tolerance band and close to its 4 per cent target. Headline retail inflation stood at 4.45 per cent year-on-year in July and 4.82 per cent in August. Given the favourable inflation environment and the growing positive economic sentiment, raising interest rates unnecessarily would have acted as a drag on private investment and consumption.
External shocks prompted the October surprise
However, things turned around in October 2026, compelling the central bank to raise rates. This was due to a combination of external shocks and a few domestic price pressures emerging simultaneously. Internationally, the re-escalation of the conflict in Asia disrupted global energy supplies, leading the RBI to change its stance on oil prices by postulating that the Indian crude basket averaged $116.1 a barrel in September, up from $82.0 in July.
Furthermore, rate hikes by the US Federal Reserve narrowed interest rate differentials, putting the Indian rupee under persistent depreciation pressure and thereby increasing imported inflation. Domestically, a deficient south-west monsoon, coupled with an El Niño weather pattern, put agricultural produce and crop yields in peril. The RBI, therefore, upgraded its FY27 CPI inflation forecast from 5.0 per cent to 5.2 per cent. In its October policy statement, the RBI estimated that headline inflation would peak at 6 per cent in Q3 FY27, hitting the upper end of its tolerance band.
The RBI’s dilemma: A demand-side tool against supply-side shocks
The central dilemma in assessing the RBI’s decision to hike the repo rate lies in its choice of tool. The tool of choice, i.e. the increase in the repo rate, is a demand-side measure that would cool demand in the economy by making short-term borrowing by commercial banks costlier.
Therefore, not all the pressure is supply-side; credit growth of 18 per cent is precisely the kind of demand a rate hike is meant to cool. Meanwhile, India’s current inflationary pressures are primarily supply-side in nature, ranging from energy disruptions on account of geopolitical tensions to disrupted freight movements and weather-induced crop yield deficits. The RBI could not possibly employ higher interest rates to create more oil or make rain fall on parched crops. However, its course of action is not without justification. This is because, should these supply-side disruptions persist, they have the potential to generate “second-round effects” by spilling over into transportation costs, services inflation, wage demands and overall price levels in India.
Raising the repo rate acts as a pre-emptive measure by anchoring inflation expectations to prevent the costs of goods and services from spiralling out of control. This pre-emptive stance is also in line with Milton Friedman’s (1961) concept of “long and variable lags” in the transmission of monetary policy. As monetary policy acts with a lag, this hike will bite after the Q3 peak, so the RBI is really targeting expectations. With monetary conditions tightening in expectation of persistent inflation, the RBI seeks to prevent transitory supply-side shocks from becoming embedded in broader price-setting behaviour.
Core inflation trends and real rates prompted the rate hike
The RBI’s decision to act against inflation was also prompted by a move in core inflation trends and the prospect of poor real rates. The central bank raised its core inflation forecast to 4.4 per cent. It was also noted that prices were spilling over to other goods and services apart from food and fuel. Before the rate hike, real interest rates (the repo rate minus inflation) were unduly low. Negative real rates discourage the public from making bank deposits, cause depreciation pressures in the foreign exchange market and, most worryingly, if Q3 inflation indeed crosses 6 per cent and remains there, real rates will turn negative, with disastrous ramifications for the currency, the bank deposit base and the overall economy. The RBI increased the repo rate to 5.50 per cent, which would now make real interest rates positive, helping the currency and the economy in the long term.
Economic growth: A cushion for tighter credit conditions
The RBI had the room to act on its fears because the Indian economy has sufficient growth momentum to withstand tighter credit conditions without slipping into a recession. Q1 FY27 real GDP growth of 7.8 per cent and an upgraded full-year growth forecast for FY27 of 7.1 per cent give the RBI confidence in taking the decision to increase the policy rate this month. The economy, with its resilient manufacturing base and services sector, and a high level of fixed investment, has enough room to absorb the impact of higher interest rates without deleterious consequences for growth.
Conclusion
The October rate hike is the RBI’s bid to safeguard price stability without stifling India’s growth momentum. Its effectiveness will depend on whether inflationary pressures subside or become embedded in domestic prices, the trajectory of global energy markets and the impact of the monsoon on food prices. Whether October was a one-off precaution or the beginning of a tightening cycle will be determined at the December meeting.